Emas sebagai penyimpan sebenar nilai kekayaan

Tips membeli dan menyimpan emas


Buy gold bars and coins instead of jewelry for investment. You may not get a good price for jewelry because of making and processing charges involved in it.

Look for hallmark or BIS sign on gold bars and coins. It is a sign of quality and purity.

Buy physical gold only from a well-known dealer or bank.

Gold should be viewed as a long-term investment.

Gold investors should not be "buy today and hope to make money tomorrow".

Gold should be seen as a store of value and insurance for your portfolio. When you buy insurance, you are not expecting to die tomorrow.


=================================================================================

Berminat untuk menjadi Dealer. PG?...hubungi saya khairul (+6012-989 7399) insya Allah saya akan bantu dari A - Z ...
===============================================================================

Promosi Dealer RM20,000.00

Pada hari Rabu 27 Okt 2010, Public Fine Gold International melanjutkan lagi promosi Dealer 20K.


Promosi ini dilanjutkan untuk tempoh 2 bulan lagi iaitu sehingga penghujung Disember 2010. Jadi, kepada sesiapa yang pernah menyimpan hajat untuk menjadi Peniaga Emas Public Gold, anda boleh hubungi saya @012-9897 399. Emas adalah sesuai untuk dibeli pada setiap masa dan sejarah harga emas tpada ahun lepas meningkat sehingga 37% dan pada tahun ini, harga emas telah meningkat lagi sehingga menghampiri 30%

Kenapa Perlu Rebut Peluang Ini?

Seperti yang telah saya jelaskan sebelum ini...Fahami ini betul2 sebelum membuat tafsiran. Modal 20k tu bukannya anda bayar tanpa mendapat apa2, tetapi anda akan dapat emas yang juga bernilai 20k. Tidak seperti kebiasaannya untuk menjadi Dealer anda perlu membeli set yang saya sebutkan di atas, tetapi kali ini anda cuma perlu membuat pilihan emas jenis apa yang anda mahukan, asalkan nilainya sampai atau lebih daripada 20k, secara automatiknya anda telah bergelar Dealer Public Gold yang sah! So, di mana kerugian anda? Ingat, Public Gold menjamin ketulenan emasnya. Dan emas yang dikeluarkan cuma jenis 999 dan 916. Jadi anda tak perlu risau jika selepas anda dapat emas tu, tiba Public Gold tutup kedai (hehe..katakanla ye). Andai terjadi macam ni, anda tak perlu susah payah pergi cari Public Gold, sebab emas anda yang bernilai 20k itu masih berada di tangan anda dan ianya diterima di mana-mana sahaja kedai emas. Kedai emas mana yang tak mahu beli emas kedai lain?

Public Gold memberi peluang untuk anda menjual emas keluaran mereka sendiri. Setiap jualan yang anda buat, anda akan mendapat komisen sebanyak 1.5%. Menarik bukan? Di samping boleh meniaga dan meraih komisen, anda sebenarnya mempunyai peluang untuk membuat keuntungan sehingga hampir 6% dari hasil jualan. Sebarang persoalan boleh lah hubungi saya.

Assalamualaikum warahmatullah dan salam sejahtera. Harap kita semua sihat sejahtera dan berada di dalam rahmat Allah sentiasa.

Sebenarnya sudah hampir setahun perkara yang sangat mengembirakan telah diwar-warkan dan saya ingin berkongsi bersama anda semua terutama bagi peminat, pelabur dan penyimpan emas (gold bullion/wafers collectors).

Public Gold menawarkan peluang perniagaan kepada individu untuk menjadi agen mereka dengan modal yang sangat berpatutan iaitu nilaian dalam kurang lebih 250g emas sahaja (RM20,000.00) bergantung kepada harga emas semasa.

Saya berpendapat peluang yang ditawarkan ini adalah sangat menarik dan perlu direbut secepat mungkin.

Imbasan kembali tentang Public Gold.

Pada 4 November 2008, Public Gold telah menawarkan peluang kepada individu, syarikat dan koperasi untuk menjadi agen mereka.

Namun modal yang diperlukan adalah tinggi, sekitar RM250,000. Jadi ia sedikit sebanyak menjadi halangan kepada mereka yang berminat untuk menceburi business emas ini, walaupun ianya adalah perniagaan yang menguntungkan.

Sekarang modal agen hanyalah RM20,000.

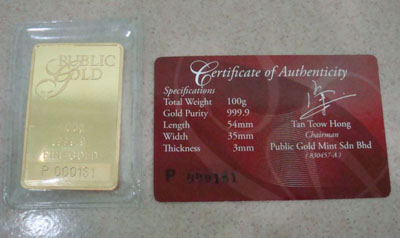
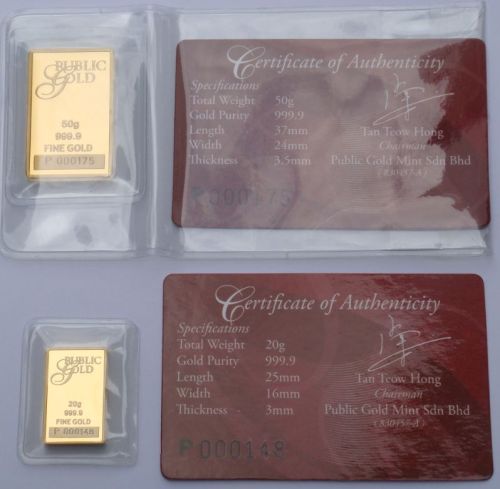
Public Gold telah membuka peluang menjadi agen kepada mereka yang berminat dengan modal yang minima. Sekarang, dengan modal RM20,000.00 anda sudah boleh menjadi agen Public Gold dan boleh mulakan perniagaan emas anda sendiri. RM20,000.00 tersebut adalah untuk belian stok emas 999.9 (starter kit - seperti gambar sebelah kiri ni) Public Gold, contohnya gold wafer 100 gram, gold wafer50 gram, gold wafer 20 gram dan dinar emas 916 (1 dinar, 5 dinar dan 10 dinar).


Pada pendapat saya modal tersebut adalah sangat berpatutan bagi business emas ini. Satu peluang keemasan yang perlu direbut segera.

Dengan menjadi agen Public Gold anda boleh membeli dan menjual produk-produk keluaran Public Gold seperti:

Gold wafer 20 gram

Gold wafer 50 gram

Gold wafer 100 gram

Gold Coin 50 gram

Dinar Emas (1 Dinar, 5 Dinar dan 10 Dinar)


Kesemua produk Public Gold adalah untuk pelaburan emas, senang dijual dan perbezaan antara harga belian/jualan lebih rendah. Very hot item


Gold Bar 20 gram, 50 gram dan gold coin 50 gram


1 Dinar, 5 Dinar dan 10 Dinar Emas 916 (22K)

Kebaikan menjadi agen Public Gold.

1. Produk Public Gold sangat mudah untuk dijual. Ini kerana Public Gold menjual emas pelaburan dengan harga yang lebih rendah berbanding harga di kedai emas. Perbezaan diantara harga belian dan jualan adalah sangat kecil iaitu di sekitar 5% - 6% sahaja berbanding dengan kedai-kedai emas diantara 10% - 18%.

2. Gold bar Public Gold tetap diterima walaupun tercalar, bengkok, kemek asalkan beratnya tetap sama (tidak berubah). Jadi, peace of mind kepada pembeli emas Public Gold ni.

3. Stok yang sentiasa ada. Walau harga emas naik atau turun, kita tetap boleh order daripada Public Gold. Tidak pernah mereka cakap stok tak ada. Stok sentiasa ada.

4. Agen diberi pamplet secara percuma oleh syarikat PG. Jadi senang untuk kita buat promosi.


Dengan pamplet, Senang sikit nak promote.

Target Jualan Bulanan.

Bagi agen yang baru dilantik, terdapat target jualan bulanan iaitu RM20,000 sebulan. Ini adalah untuk memastikan agen-agen yang dilantik memberikan komitmen di dalam business ini, bukan semata-mata hendak membeli emas dengan harga diskaun. Bagi saya, sales RM20,000 sebulan memang mudah untuk tercapai jika berusaha lebih sedikit, yang penting kesungguhan dan minat yang mendalam perlu ada dalam diri agen masing-masing

Kesimpulan.

Ini adalah satu peluang keemasan yang terbaik. Jika anda mempunyai modal RM20,000.00 dan juga berkeinginan untuk mencari peluang perniagaan yang menguntungkan, maka menjadi agen Public Gold merupakan pilihan yang terbaik. Bukan sekadar mendapat keuntungan, malahan menyediakan ruang dan peluang bagi kita untuk berkongsi ilmu berkenaan kepentingan emas dengan masyarakat di luar sana. Kita beroleh keuntungan, mereka beroleh manfa'at dari ilmu yang kita berikan, sama-sama mendapat keuntungan dan manfa'at.

Jika berminat,
Hubungi saya Khairul Annuar Ismail (PG000203) nuar96@yahoo.com

Jika anda berminat untuk menjadi agen Public Gold walaupun anda tidak dapat menyediakan modal sebanyak RM20,000.00, anda boleh menghubungi saya dengan menghantar pertanyaan ke email nuar96@gmail.com ataupun letakkan di bahagian komen atau call me@++6012.9897.399. Saya amat berbesar hati sekiranya dapat membantu anda menjadi usahawan emas yang berjaya.

Apa tunggu lagi, rebutlah peluang ini sekarang!


Thursday, August 20, 2009

10 Rules of Multiplying Personal Wealth

Rule 1: Be systematic, unemotional and diversified

This is the very first rule we touch on right from the beginning. There's a popular bumper sticker that says, "I'm spending my grandkids' inheritance."

That whole idea just frustrates me. In some ways, our society's personality is such that if we can spend our money before we die, we've lived a great life. But you can't do that.

Rule 2: Never spend principal

That's the second rule. Inflation has gone above 10 per cent in the US economy five times, and I'd bet you it will happen again.

Rule 3: Never borrow money to buy a depreciating asset

Almost everybody does this at some point. But as soon as possible, and definitely by retirement, you have to get back to a cash basis.

How many people know what a $30,000 car bought on credit costs them at age 25? In retirement dollars, at age 65 and assuming a hypothetical 10 per cent return, that financed car could cost as much as $11,314 a month in potential income. Forever!

So, do you or your children understand what an "investment" in a car really costs you? Yes, I know we all buy cars. But try to imagine what would happen if I got every 25-year-old to forgo just one car purchase and invest that same amount of money in their long-term retirement goals. What a huge difference that could make to their choices at retirement!

Rule 4: Never save money in a spending account

Keep separate bank accounts for saving and spending. You have to save in savings accounts. If you truly want those savings to grow, use an account that helps you leave the money at work, rather than a "slush fund" that's easy to dip into.

People tell me they are saving $545 a month in an account. Yet when I ask them how much they have accumulated after seven years of doing this, their answer is often $1,123 because they spend out of that same account.

It is not a save-to-save account -- it's a save-to-spend account! If you know you're not naturally a disciplined saver, make it harder to get at the money. You'll be doing yourself a favor in the long run.

Rule 5: Use half, save half

Every time you pay off a debt, get a pay raise, get a bonus, or have any excess cash, have fun with half the money, and put the other half toward your long-term goals.

This is one of the best rules, especially for younger people. By following this rule consistently, in ten years, most people are amazed at how much they can save.

Whether you save or not has nothing to do with how much money you make. Either you save or you don't. It's a habit. Make a habit of investing half of any windfall, big or small, right off the top.

Rule 6: Always use matching money

For example, your employer's 401(k) matching program (in India, the employer's matching Providend Fund Contribution, for example).

Do whatever you must to take advantage of matched contributions in a retirement plan. You can't afford not to take the free money.

Hypothetically speaking, if you invest $100 take-home pay in a taxable investment (25 per cent tax on growth) at an assumed 10 per cent return, you would potentially have $135,586 in 30 years (sales charges and fees not included).

If you put the same $100 into your 401(k) that is 100 per cent matched, now you have $150 a month saved because of the tax savings.

Meanwhile your boss adds $150 because of the match -- and it grows tax-deferred, too! Using the same hypothetical return scenario, we have $683,797 to live on -- five times as much wealth with the same work.

Sometimes being smart with our money is a phenomenal advantage. This is a classic example of where investor behavior, not investment performance, makes a huge difference in your long-term wealth potential. You can hate your boss, or plan to quit, but you must take advantage of the matched money.

Rule 7: Do not spend more than you make

This should seem painfully obvious, but people often have no idea how much they're really spending and what relationship that has to how much they make.

In making a budget people often cannot account for 30 per cent of the money they earn and where it goes.

If you are just a little more vigilant, you can significantly enhance your long-term ability to reach your goals.

A budget doesn't happen by accident; it takes practice and is an ever-changing tool in our financial planning. Practice makes perfect. Although "perfect" is never the ideal word for a budget, it does have more meaning and usefulness the longer we practice its use.

Rule 8: Never leave undivided real property to joint beneficiaries

Lots of things are more important than money. Family is probably at the top of the list. If you want a vicious family feud on your hands, breaking this rule would be a great place to start.

Imagine a farm that gets left to four sons: One has farmed it for 20 years; one is an environmentalist and wants it to be a park; one is broke and needs money; and one could not care less about it. Who will get wealthy from this plan? The attorneys. And the kids and grand-kids will probably hate each other forever.

Remember that 'equal', 'equitable', and 'fair' are three different words with three totally different meanings.

Rule 9: Never name co-trustees or co-executors of your estate

This one goes right along with the undivided property rule above. Next to poor planning, litigation can be the biggest financial drain on an estate.

Minimize the number of trusted decision-makers, and you'll reduce your chances for litigation. What's more, the entire process will be easier and more efficient with one decision-maker.

Rule 10: Above all --

Be happy with what you have, and it will lead to both unbelievable financial success and personal (not mere financial) wealth!


Sunday, August 16, 2009

Zakat for Gold...

The second important duty of servanthood is zakat. God's Messenger, who depicts prayer as Islam's pillar or support, describes zakat as its bridge (Canan, ibid., 6:346), for zakat not only brings the social strata closer to each other and fills in the gaps between them and their members, but also stops such gaps from forming.
Zakat means purity and growing. Since it purifies wealth and people's attachment to it, and causes both it and Muslims to grow in purity and sincerity, the Qur'an calls it zakat (or the prescribed alms):

(O Messenger,) take alms (prescribed or voluntary) out of their wealth so that you may cleanse them thereby and cause them to grow in purity and sincerity, and pray for them. Indeed your prayer is a source of comfort for them. God is All-Hearing, All-Knowing. (9:103)

Taking into account its very nature, zakat constitutes one of Islam's five pillars. It is associated with prayer (salat) in 82 Qur'anic verses. God, the Exalted One, prescribed it in His Book (the Qur'an), His Messenger corroborated it by his sunna, and the Muslim community by consensus upheld it. Ibn 'Abbas reported that when the Prophet sent Mu'adh ibn Jabal to Yemen (as its governor), he said to him:

You are going to a people who are People of the Book. Invite them to accept the shahada: that there is no deity but God and I am His Messenger. If they accept and affirm this, tell them that God, the Glorious One, has enjoined five prayers upon them during the day and night. If they accept that, tell them also that He has enjoined sadaqa (meaning zakat) upon their assets, which will be taken from the rich of the (Muslim) community and distributed to the poor. If they accept that, refrain from laying hands upon the best of their goods and fear the cry of the oppressed, for there is no barrier between God and it. (Bukhari, "Zakat," 1:41; Muslim, "Iman," 31.)

Many verses exhort Muslims to pay zakat and forbid hoarding wealth. For example:

The believers, both men and women, they are guardians, confidants and helpers of one another. They enjoin and promote what is right and good and forbid and try to prevent the evil. They establish the prayer in conformity with its conditions, and pay the zakat (prescribed purifying alms) fully. They always obey God and His Messenger. Those are the distinguished ones whom God shall treat with mercy. Assuredly, God is the All-Honored with irresistible might, All-Wise. (9:71)

and:

Those who hoard gold and silver and do not spend it in God's way (to exalt His cause and help the poor and needy: O Messenger,) give them the glad tidings of a painful chastisement. (9:34)

Who Must Pay
Zakat must be paid by every free Muslim, man or woman, who has a nisab (the required amount of wealth). As for the insane and children who have a nisab, if their wealth is under disposal or in circulation, their guardians pay it on their behalf. If a person dies before paying it, it must be taken from the estate before paying off any debts, if there are any, and the heirs share the inheritance.

Conditions for Nisab. Nisab is conditioned by the following:

  • Nisab is the amount of wealth remaining after meeting all expenses for such vital necessities as food, clothes, housing, and a mount. Thus, one does not have to pay zakat on what he or she needs to make a living, such as tools or machines related to carpentry, farming, tailoring, or working as a doctor. All debts are subtracted from one's wealth. If one has enough secured credit to pay off the debt, it is added to one's wealth, and if the resultant wealth reaches the nisab, one must pay zakat.
  • For many items subject to zakat (e.g., money, gold, silver, and cattle), a full year of the Islamic calendar should pass, starting from the day of the nisab's possession. If the wealth possessed decreases during the year but is still possessed one year later, zakat must be paid. What matters is the availability of nisab at the beginning and end of the year. However, this condition does not apply to plantations and fruits, for their zakat should be paid, or at least calculated, on the harvest day and include what has been consumed before the harvest.
  • In short, there are two types of zakat: one grows by itself (e.g., crops and fruits), and the other is used for growing and production (e.g., money, merchandise, and cattle). In the former case, zakat should be paid at harvest time; in the later, at the end of the year.
  • The wealth subject to zakat should be actively or potentially increasing, growing, or productive. This condition will be explained below.
  • One must have private, doubtless ownership or possession and the right of disposal of the wealth liable to zakat.

Intention. Since paying zakat is an act of worship, its validity depends upon one's sincere intention to pay it for God's sake. If one pays it without making the intention, one can still intend while the wealth expended as zakat has not yet been consumed.

Paying Zakat at Its Due Time. Zakat must be paid immediately at its due time. Deferring it is prohibited, unless there is a valid reason not to do so.

Holdings Subject to Zakat and Their Nisab. Islam enjoined zakat on currencies and similar things, such as shares, bonds and checks, gold and silver, crops, fruit, livestock, merchandise, minerals, and treasure.

The Standard of Richness. Islam does not criticize earning; rather, it encourages working and earning one's livelihood. But it does not approve of earning for luxury and a luxurious life, and urges Muslims to work, earn, and live for the other life as their goal. It encourages mutual helping in society and spending in God's way and for the needy, and has not established a fixed standard of living. It regards having a house, a mount, two suits and other articles of clothing, and one month worth of livelihood (some say that one can keep a year of livelihood at the most) as the necessary commodities or wealth upon which one does not have to pay zakat. Bediüzzaman Said Nursi expresses a standard that can be valid for all times, as follows: While most Muslims are below the average standards of living, a Muslim cannot live a luxurious, comfortable life.

The Sunna has established approximately 90 grams of gold or about 600 grams of silver or 40 sheep or 30 heads of cattle or 5 camels as the standard. If, according to the place or the general standard of living of the people in a particular place, one has banknotes, merchandise, or other kinds of increasing income or capital whose value is equal to any of the standard values given, he or she must pay zakat. However, in establishing the nisab, the minimum amount or value, which favors the poor, is considered.

The Nisab and Zakat for Different Items of Wealth

The Nisab and Zakat for Gold, Silver, and Other Jewelry. The nisab for gold is 20 dinars (approximately 90 grams) and for silver is 200 dirhams (approximately 600 grams), both being owned for one year. The due on them is one-fortieth of their value. Any additional amount is to be calculated in this manner. Gold and silver are combined. Thus, if one has gold and silver whose value is equal to 200 dirhams of silver, zakat must be paid. Likewise, gold, silver, banknotes and the like, and commercial merchandise are also combined. Things made of gold and silver are treated like gold and silver. In other words, if the weight of gold and silver they contain amounts to the nisab, their zakat is paid.

Although most of the scholars opine that no zakat has to be paid on diamonds, pearls, sapphires, rubies, corals, or other precious stones that women wear as ornaments and unless they are used for trade, it is piety and a measure to be saved from the obligation of zakat, which is both God's and people's right on rich people, to make some payment due to them. One should not buy such precious stones in order to avoid paying zakat.

...more on
Zakat for Different Items of Wealth

Is Gold Money ?

Is Gold Money?

As someone who has been interested in gold for the last forty years, I have always been interested in the definitions which can be applied to gold. Is gold money? It often has been, but it is not at present. I suspect it may become money again. Is gold a commodity? I think the answer to that question is “yes”. Gold used in chemical reactions, or in jewellery, is plainly a commodity which can sometimes be replaced by another commodity.

However, the question I find most interesting is whether gold is a real asset. One of the problems of investment is that there are two variables, reality and liquidity. Land or property are relatively illiquid, but are also real, in that they have a use which does not depend on their value in exchange. Gold is highly liquid, indeed it is more liquid than paper money. In extreme circumstances, paper money can lose all its value, when gold is still acceptable as payment. In 1940, when the French Army was defeated, many French people took to their automobiles to escape the advancing Germans. They found that petrol stations would not accept paper francs, but would sell their petrol in exchange for gold coins.

Gold also remains an acceptable currency in periods of high inflation, when paper money can lose all its value.

What does “reality” mean, when applied to an investment? Obviously we talk about “real estate” to describe the legal possession of property. I think that means property with a permanent character and at least a potential use. In the same way, the traditional theorists of the gold standard would say that gold was a real currency, because it has permanence and a potential non-monetary use.

I accept that reality in an asset is a relative factor. In an ideal world, we would all like to hold our financial needs in a currency with a high degree of permanence, strong alternative uses and high liquidity. We have to make do with currencies which fall short of perfect “reality”, and fall short of perfect liquidity as well. We make do with imperfect currencies because we have no choice.

Gold makes one think about these issues, but it makes one even more uneasy about electronic money. In book publishing, I am well aware of the library demand for archival books which can reasonably be expected to last for centuries, like the printed works of earlier centuries. We need also to have permanent money, which can be relied upon to survive, even though its value may decline over time. The historic value of gold has been astonishingly stable over centuries.

In an extreme example, one could be worried about the issue of money and about its preservation. Mr. Madoff has shown that fraud can reach the unbelievable level of $50 billion. Might there not be still larger frauds, so large as to achieve what the wartime German operation attempted, a complete takeover of a targeted currency?

Cybercrime is already operating on a huge scale. Suppose that Al Qaeda, instead of attacking the twin towers, had attacked the electronic systems which record all the monetary holdings of New York. No lives might have been lost, but an electronic pulse might have erased one of the central counting houses of world finance. The world might have been ruined.

Is there not some element of this cybercatastrophe in the present world crisis? Reality may be a variable concept, with nothing 100 per cent real and hardly anything zero per cent. When I was born, in 1928, gold was money, and gold was over 90 per cent real. In 1970, when I was in my forties, money was paper, and even the convertibility into gold of the Bretton Woods Agreement was breaking up. Now money is a largely unidentifiable electronic pulse, itself vulnerable to attack by electronic means. Virtual money has very low reality, much lower than paper. Surely this is a system which could be blown away because there is nothing in it to gain confidence. Even a return to paper money would raise the level of reality attached to world currencies. There is a problem of raising the reality level of all currencies – a problem which nineteenth century economists solved by convertibility to gold.

Source : Is Gold Money? by William Rees-Mogg

Fakta Emas

Fakta

  • Ahli kimia tidak pernah berjaya menghasilkan emas tiruan kerana sifat logam berkenaan sukar ditiru.

  • Sifat emas tulen adalah lembut paling boleh ditempa dan dibentuk.

  • Emas asli boleh disahkan tulen melalui dua cara mudah iaitu apabila digigit, ia meninggalkan kesan lekuk gigi, kedua apabila dibakar atau dicairkan, ia tidak berubah warna.
  • Thursday, August 13, 2009

    Public Gold Authorised Agents


    Produk jualan kami ialah emas keluaran Public Gold seperti di bawah :

    1) Emas Keping / Bar Public Gold – berat 20g, purity 24k, 999.9

    2) Emas Keping / Bar Public Gold – berat 50g, purity 24k, 999.9

    50g20g

    3) Emas Keping / Bar Public Gold – berat 100g, purity 24k, 999.9

    100gram


    Our Dinar PDF Print E-mail

    Gold Dinar Coins

    Dinar 1
    Ingot dinar_1.png
    Diameter 18mm
    Metal Au
    Weight 4.25g
    Thickness 0.72mm
    Purity 916
    Dinar 5
    Ingot dinar_5.png
    Diameter 32mm
    Metal Au
    Weight 21.25g
    Thickness 1.5mm
    Purity 916
    Dinar 10
    Ingot dinar_10.png
    Diameter 38mm
    Metal Au
    Weight 42.5g
    Thickness 2.18mm
    Purity 916

    Harga jualan – mengikut harga semasa di laman http://publicgold.com.my dan http://publicdinar.com/ atau

    LIVE GOLD PRICE charts: Live Gold Price

    Public Gold Authorised Dealers –

    EN KHAIRUL ANNUAR ISMAIL (+6012.989.7399 )

    EN. NIZAM AZWADI ALI (+6017.952.6772)

    EN. SUHAIMI BIN MUSTAPA (+6014.864.0863) Tawau, Sabah

    EN. ASMADI BIN ALI (+6019.948.4001)

    TUAN HJ. UBAIDILLAH BIN HARUN (+6017.935.6113)

    EN. ADIE IRMAN ABDULLAH (+6019.982.9025)

    EN. ABDUL GHANI AYOB (+6017.905.8031)

    EN. MOHD IMERAN ABDULLAH (+6019.915.4677)

    EN. MOHD NOR MAIZATUL ADZHA MUHAMMAD (+6019.958.5454) Batu Buruk, Besut dan sekitarnya

    EN. MOHD RIDZUAN MAMAT (+6019.986.5054)

    EN. MOHD RIDHUWAN MOHD ZAMLI (+6017.932.3176) Ampang, Kuala Lumpur

    EN. MOHD YUNUS ZAKARIA (+6019.930.0130)

    EN. AHMAD NAZIR HARON (+6019.934.8673)

    EN. MOHD NOR AZLAN AYOB (+6017.953.6500)

    EN. SHARIF AKBAR AHMAD AKIL (+6019.911.0313)

    EN. MOHD NOR AFFENDY MOHD ALI (+6013.920.1974)

    EN. MOHD MAZHAIRIL ADRI ABDUL HAMID (+6012.958.8678)

    EN. WAN MOHD WAZIR WAN ABDUL WAHAB (+6019.936.2935)

    EN. YUSMANIZAM BIN YUSOF (+6013.257.8630) Besut, Jerteh, Pasir Puteh

    EN. MUHD NOR KHUSYAIRY BIN MUHAMMAD KHARIRI (+6013.227.1092) Besut, Jerteh, Pasir Puteh


    Lokasi – KUALA TERENGGANU + TERENGGANU + MALAYSIA

    Delivery charges:

    Item

    Transportation Cost for West Malaysia (RM)

    Transportation Cost for East Malaysia (RM)

    Gold Bar 20 grams

    10

    20

    Gold Bar 50 grams

    20

    40

    Gold Bar 100 grams

    30

    60

    Kilobar 1000 grams

    500

    1000

    Gold Coin 50 grams

    20

    40

    (Inclusive all costs, Ex Penang, Malaysia)

    Tuesday, August 11, 2009

    Gold Investment Tips | Tips Pelaburan Emas

    For centuries, gold has remained a precious and treasured commodity - one that has held men and women in its splendor and glitter. But have you considered investing in gold or looked at gold investment as part of your investment plan? Gold as an investment has been resorted by the wealthy families in Europe and Asia for centuries. Precious metals are a good investment opportunity as they are portable and compact. Read up our tips on gold investment.


    Investing in Gold

    Gold prices have seen an upward trend in the past 3 years. Though the earlier decades saw a relatively poor performance by the precious metal, gold prices are likely to rise steadily over the longer term. This investment opportunity is showing an upswing again. With uncertainty in the stock market and decline in the US dollar, investors are taking a fresh look at gold as an investment option. Gold works as a perfect hedge against investment in other assets.


    In fact, when other investments take a beating, gold investment tends to stabilize. As a long term investor, holding on to gold investment is a good tip. When you are planning to invest in gold, it would be wise to consult an investment consultant. He can help you match your investment goals with the right type of gold purchase. An investment firm can aid in making the right choice of gold investment products so as to hedge your portfolio.

    Gold bullion coins work well for those who want to capitalize on price movements of the precious metal. It is prudent to buy gold when its prices are low. But sometimes getting the right price may not be that easy. The same holds good for selling too. A buyer should not look at merely the price of the gold investment but its percentage over the gold price or the premium.


    Gold investment options

    Bullion coins are an excellent investment option. You can go in for the American Eagle, Canadian Maple Leaf, Britannia or the Australian Nugget. The American Eagle Gold coins were minted first in 1986 and hold pride of place as the world's leading gold coin investment option. These gold coins are struck in 22 karat gold with the total weight as stamped on the reverse of the coin. Silver and copper are also used so as to protect the gold finish. Special dyes are used to strike these gold coins to ensure that minute details are visible.


    Such American Gold Eagles can be bought at dealers of precious metals and coins. You can buy them at the prevailing price of gold and a premium for distribution costs. Gold coins are universally recognized and can be easily sold. The South African Krugerrand was the first gold bullion coin that was marketed as an investment opportunity. The one-ounce Kruggerand gold bullion coin is extremely popular.


    • Gold bars are another investment option. Smaller bars cost more as the premium is low on larger bars. But resale of big bars is not easy. Gold coins are available at lower premiums as compared to gold bars.

    • Gold certificates are titles for a stipulated amount of gold. You can take physical delivery of the gold or trade on it through the certificates. Another scheme is to go in for a gold accumulation plan - one that allows you to buy gold for a fixed sum each month. This allows you to benefit from acquiring it at a market average price.

    • Gold accounts can be started with major banks. Typically those speculating in gold usually resort to this sort of account with commodity brokers or private bankers.

    • Gold mining shares are another method of investing in gold, though not directly. Increase in gold bullion prices will lead to an increase in gold mining share prices - On this premise, many investors take up gold mining shares.

    Preserve gold bars and bullion coins in the original mint packaging. Since it is soft, mint-fresh gold is easily subject to scratches from rough surfaces. Careful handling and preserving can go a long way in getting the best price during a resale.


    Source : Gold Investment Tips

    Sunday, August 9, 2009

    Why GOLD ?


    A DIFFERENT CLASS OF ASSET:

    Most investment portfolios are invested primarily in traditional financial assets such as stocks and bonds. The reason for holding diverse investments is to protect the portfolio against fluctuations in the value of any single asset class.

    In building an investment portfolio, investors should avoid unnecessary risk through wise diversification. Diversification is the allocation of investable funds to a variety of investments. By diversifying, investors can reduce the risk that they would otherwise bear. Also, the risk reduction benefits of diversification can be achieved without reducing the overall return on your portfolio.
    The Power of Diversification

    The key to diversification is finding investments that are not closely correlated with one another. Other things being equal, the less the correlation between two investments, the better suited they are for effective diversification. This gives rise to a problem for most investors because most stocks are relatively closely correlated with one another and most bonds are relatively closely correlated with each other. In addition, there is also a close correlation between stocks and bonds. Investors need to find investments that are not closely correlated to stocks and bonds and include them as additional elements in their portfolios.
    Diversification Reduces Risk

    Many investors combine tangible assets with their stock and bond portfolios to reduce risk. This is due to the fact that tangible assets have historically had a very low, even negative, correlation with stocks and bonds. This means that they are useful to hold in conjunction with paper investments in order to reduce total risk. Not only is the risk reduced due to negative correlation between tangible and paper assets, but tangible assets have produced exceptional investment returns on their own. Every sign today points to increasing importance for diversification; that also means increasing importance for tangible assets.
    I. GOLD – STORE OF VALUE

    One major reason investors look to gold as an asset class is because it will always maintain an intrinsic value. Gold will not get lost in an accounting scandal or a market collapse. Economist Stephen Harmston of Bannock Consulting had this to say in a 1998 report for the World Gold Council,

    “…although the gold price may fluctuate, over the very long run gold has consistently reverted to its historic purchasing power parity against other commodities and intermediate products. Historically, gold has proved to be an effective preserver of wealth. It has also proved to be a safe haven in times of economic and social instability. In a period of a long bull run in equities, with low inflation and relative stability in foreign exchange markets, it is tempting for investors to expect continual high rates of return on investments. It sometimes takes a period of falling stock prices and market turmoil to focus the mind on the fact that it may be important to invest part of one’s portfolio in an asset that will, at least, hold its value.”

    Today is the scenario that the World Gold Council report was referring to in 1998.
    II. GOLD - PORTFOLIO DIVERSIFIER

    The most effective way to diversify your portfolio and protect the wealth created in the stock and financial markets is to invest in assets that are negatively correlated with those markets. Gold is the ideal diversifier for a stock portfolio, simply because it is among the most negatively correlated assets to stocks.

    Diversification: The Key to Gold Investing

    One of the most important aspects of investing is the control of risk in your portfolio, relative to the expected return. Tangible assets are an extremely useful tool for investors in that regard.

    Portfolios that contain gold are generally more robust and better able to cope with market uncertainties than those that don’t.

    Adding gold to a portfolio introduces an entirely different class of asset. Gold is unusual because it is both a commodity and a monetary asset. It is an ‘effective diversifier’ because its performance tends to move independently of other investments and key economic indicators.

    Recent independent studies have shown that traditional diversifiers (such as bonds and alternative assets) often fail during times of market stress or instability. Even a small allocation of gold has been proven to significantly improve the consistency of portfolio performance during both stable and unstable financial periods.

    There are six primary reasons why investors own gold:

    1. As a hedge against inflation.
    2. As a hedge against a declining dollar.
    3. As a safe haven in times of geopolitical and financial market instability.
    4. As a commodity, based on gold’s supply and demand fundamentals.
    5. As a store of value.
    6. As a portfolio diversifier.

    III. HEDGE AGAINST INFLATION

    Gold is renowned as a hedge against inflation. The most consistent factor determining the price of gold has been inflation - as inflation goes up, the price of gold goes up along with it. Since the end of World War II, the five years in which U.S. inflation was at its highest were 1946, 1974, 1975, 1979, and 1980. During those five years, the average real return on stocks, as measured by the Dow, was -12.33%; the average real return on gold was 130.4%.

    Today, a number of factors are conspiring to create the perfect inflationary storm: extremely stimulative monetary policy, a major tax cut, a long term decline in the dollar, a spike in oil prices, a mammoth trade deficit, and America’s status as the world’s biggest debtor nation. Almost across the board, commodity prices up despite the short-term absence of a weakening dollar which is often viewed as the principal reason for stronger commodity prices.

    Oil, Inflation and Gold
    Although the prices of gold and oil don’t exactly mirror one another, there is no question that oil prices do affect gold prices. If oil prices rise or fall sharply, investors can expect a corresponding reaction in gold prices, often with a lag. There have been two major upward moves in the price of gold since it was freed to float in 1968. The first occurred between 1972 and 1974 when oil prices climbed 325%, from US$2.44 to US$10.36. During the same period, gold prices rose 268% (on a quarterly average basis) from US$47.45 to US$174.76. The second major price move occurred between 1978 and 1980, when oil prices increased 105%, from US$12.70 to US$26.00. Over the same period, quarterly average gold prices rose 254% from US$178.33 to US$631.40.
    IV. GOLD - HEDGE AGAINST A DECLINING DOLLAR

    Gold is bought and sold in U.S. dollars, so any decline in the value of the dollar causes the price of gold to rise. The U.S. dollar is the world’s reserve currency - the primary medium for international transactions, the principal store of value for savings, the currency in which the worth of commodities and equities are calculated, and the currency primarily held as reserves by the world’s central banks. However, now that it has been stripped of its gold backing international banks and Countries are reviewing there currency reserve options
    V. GOLD AS A SAFE HAVEN

    Despite the fact that the United States is the world’s only remaining superpower, there are a myriad of problems festering around the world, any one of which could erupt with little warning. Gold has often been called the “crisis commodity” because it tends to outperform other investments during periods of world tensions. The very same factors that cause other investments to suffer cause the price of gold to rise. A bad economy can sink poorly run banks. Bad banks can sink an entire economy. And, perhaps most importantly to the rest of the world, the integration of the global economy has made it possible for banking and economic failures to destabilise the world economyAs banking crises occur, the public begins to distrust paper assets and turns to gold for a safe haven.

    When all else fails, governments rescue themselves with the printing press, making their currency worth less and gold worth more. Gold has always risen the most when confidence in government is at its lowest.
    VI. GOLD - SUPPLY AND DEMAND

    First, demand is out pacing supply across the board. Gold production is declining; Copper production is declining; the production of lead and other metals is declining. It is very difficult to open new mines when the whole process takes about seven years on average, making it hard to address the supply issue quickly. Gold output in South Africa, the world’s largest gold producer, fell to its lowest level since 1931 this past year as the rand’s gains prompted Harmony Gold Mining Co. and rivals to close mines despite 16 year highs in the gold price.

    Growing Demand - China, India and Gold India is the largest gold-consuming nation in the world. China, on the other hand, has the fastest-growing economy in modern history. Both India and China are in the process of liberalizing laws relating to the import and sale of gold in ways that will facilitate gold purchases on a mammoth scale.

    China is teaching the West something new. Its economy, growing at 9 percent per year, is expected to become the second largest in the world by 2020, behind only the United States. Last year Americans spent $162 billion more on Chinese goods than the Chinese spent on U.S. products. That gap has been growing by more than 25 percent per year. China’s consumer class, meanwhile, is spending on everything from bagels to Bentleys – and will soon outnumber the entire U.S. population. China’s explosive growth “could be the dominant event of this century,” says Stapleton Roy, former U.S. Ambassador to China. “Never before has a country risen as fast as China is doing.”
     

    Where you from

    Who's online

    Tips Pelaburan Emas | Gold Investment Tips